What is a payday loan?
A payday loan is a short-term, high-cost loan you repay in one payment on your next payday. The Consumer Financial Protection Bureau (CFPB) says these loans are generally for $500 or less and are typically due two to four weeks after you borrow. Online, you fill in one form, and lenders decide whether to make you an offer.
Loans-Payday.com is a free referral service for payday loans online, not a lender; we may be paid by lenders in our network.
To repay, you usually write a post-dated check for the full balance, including the fee, or authorize the lender to withdraw the money electronically from your bank or credit union account, according to the CFPB. If you don’t repay by the due date, the lender can cash the check or take the money from your account. Some states let lenders roll over a loan, meaning you pay only the fee and the lender moves the due date out, while the full balance stays unpaid.
The price is the catch. A fee of $15 per $100 borrowed is common, and on a two-week loan that fee equals an annual percentage rate (APR), the yearly cost of the loan including fees, of almost 400%, according to the CFPB guide to payday loan costs and fees. Repeat borrowing raises the total. In a March 2014 report, the CFPB found that four out of five payday loans were rolled over or followed by a new loan within 14 days. To see what a specific amount and fee would cost you, try the payday loan calculator.
Cheaper credit may be open to you. Federal credit unions can offer payday alternative loans (PALs), small loans of up to $2,000 repaid over one to 12 months, with application fees capped at $20 under National Credit Union Administration (NCUA) rules. While the NCUA’s temporary 18% rate ceiling stays in place, now extended to September 10, 2027, the PAL rate cap is 28%. Taking a payday loan to pay off another one adds a new fee without reducing the debt. The guide to payday loan alternatives compares more options.
How is a referral service different from a store or a single lender?
A referral service sends your one request to several lenders instead of just one. When you submit the form on Loans-Payday.com, we pass it to lenders in our network, and a lender that wants to make an offer contacts you. Loans-Payday.com does not make credit decisions, set fees or fund loans; the lender that makes the offer does. Lenders may run a soft or hard credit check, but the CFPB says payday lenders generally don’t use your credit reports or scores to decide whether you’re eligible, and some use information from specialty credit reporting companies instead. The privacy policy explains how your information is shared.
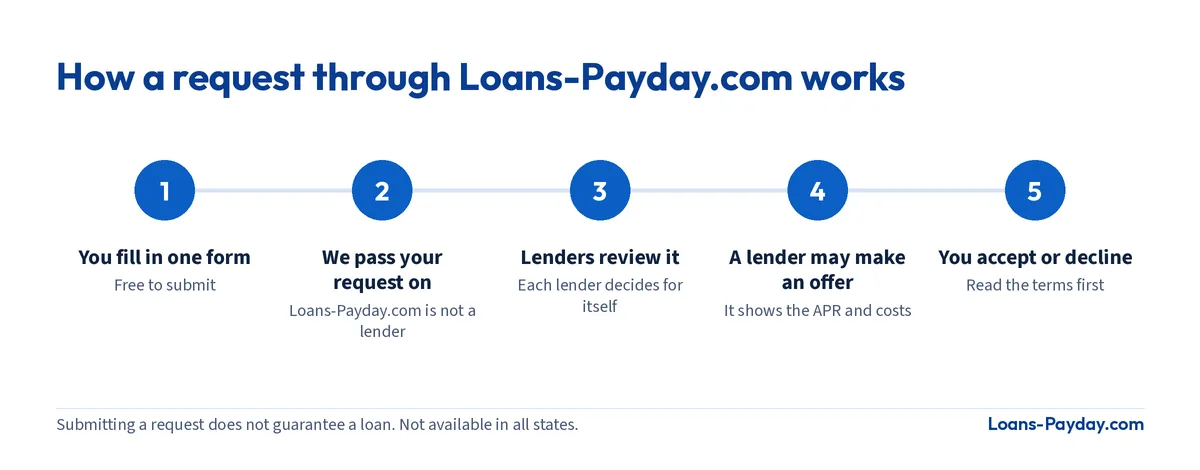
An offer does not commit you to anything. Before you agree to a payday loan, the lender must disclose the APR and other costs, according to the CFPB, which notes that the APR lets you compare the cost of different loans on the same basis. If the terms don’t fit your budget, you can say no.
| What changes | Storefront lender | Online lender, applying directly | Online referral service (Loans-Payday.com) |
|---|---|---|---|
| How you apply | In person at the store | On that lender’s website | One form, passed to lenders in a network |
| Who reviews the request | That lender | That lender | Each lender that receives it |
| Who sets the fee | The lender, within state law | The lender, within state law | The lender that makes the offer, within state law |
| How you usually repay | Post-dated check or electronic withdrawal | Electronic withdrawal from your account | Set by the lender whose offer you accept |
| What to check first | The lender’s state license | The lender’s license in your state | The license of each lender that makes an offer |
Repayment methods as described by the CFPB in “What is a payday loan?” Terms vary by lender and state.
Is a payday loan near me better than one online?
Neither is cheaper by rule, because in both cases the lender sets the fee within your state’s limits. The difference is how the money moves. Online lenders usually deposit the loan in your bank account and collect repayment through an automatic electronic withdrawal, which you approve when you sign an ACH authorization. If your account is short on the due date, that withdrawal can set off bank fees on top of the loan cost. A CFPB study released in April 2016, based on 18 months of data on more than 330 online lenders, found that about half of online borrowers had at least one withdrawal attempt that overdrafted or failed, and those borrowers paid an average of $185 in bank penalties.
You can stop a lender from taking payments electronically. The CFPB says to tell the lender you are taking away your permission for automatic payments and to tell your bank or credit union that you have revoked the authorization. You still owe the balance after you revoke it. If repayment is already hard, the guide on what happens if you can’t repay a payday loan explains your options.
How much can you borrow with a payday loan?
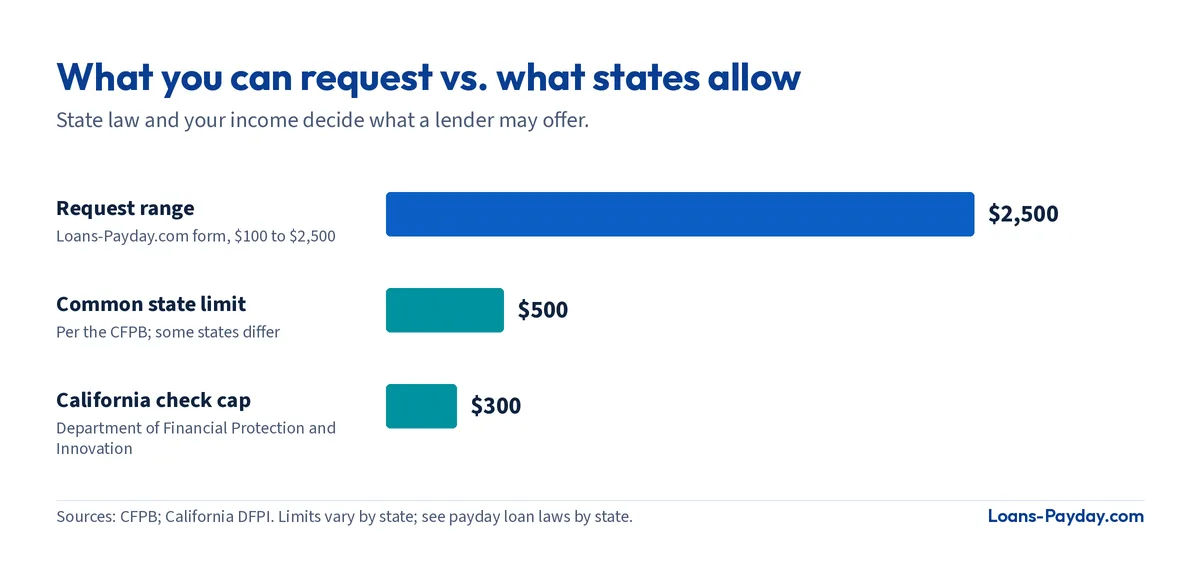
You can request $100 to $2,500, but state law and your income decide what a lender may offer. The CFPB says a common state limit for a payday loan is $500, with limits above and below that amount in other states. California, for example, caps the check you write at $300 and the fee at 15% of the check, according to the state’s Department of Financial Protection and Innovation (DFPI). Lenders also look at what you earn, so two people in the same state can receive different offers. Some lenders offer installment loans repaid over several paychecks in states that allow them; the installment loans guide explains how they differ.
How fast can you get a payday loan online?
Lenders may fund a payday loan as soon as the next business day, and sometimes the same day. Timing depends on the lender, the time you send your request and how your bank handles deposits, so no lender or referral service can promise when the money will arrive. A request sent at night, on a weekend or on a bank holiday may take longer. Many online lenders check your identity, income and bank account electronically, so you usually don’t need to fax anything. The page on faxless payday loans explains what lenders verify instead.
Be wary of any site that promises same-day approval or a guaranteed loan. The Federal Trade Commission (FTC) says banks and other legitimate lenders won’t promise or guarantee you a loan before you apply, and it calls any upfront fee a lender wants before granting the loan “a cue to walk away.”
Are payday loans legal in every state?
No, some states ban payday loans or cap rates so low that lenders don’t operate there, according to the CFPB. On July 9, 2025, the Center for Responsible Lending (CRL) reported that Rhode Island had become the 21st state, alongside the District of Columbia, to prohibit triple-digit interest rate credit; Rhode Island’s 36% cap takes effect January 1, 2027. In states that allow payday loans, many cap fees at $10 to $30 per $100 borrowed, according to the CFPB. Loans-Payday.com is not available in all states. For the rules where you live, see payday loan laws by state.
Two more points apply in every state. If you are on active duty, including active Guard or Reserve duty, or you are a covered dependent, the Military Lending Act caps the Military Annual Percentage Rate (MAPR) at 36% on most consumer loans, according to the CFPB. The FTC also says lenders must register where they do business, and you can check a lender with your state attorney general or your state’s banking or financial services regulator.
Guides to read before you borrow
These ten guides cover costs, state rules, eligibility and what to do if repayment gets hard.
- How payday loans work covers each step from request to repayment, with the costs and risks at each stage.
- Payday loan requirements lists what lenders usually ask for and how they verify it.
- Payday loans with bad credit explains how lenders review a low score and what “no credit check” ads leave out.
- Cash advance compares payday cash advances, credit card cash advances and cash advance apps.
- Installment loans shows how loans repaid over several payments differ from single-payment payday loans.
- Faxless payday loans explains how lenders check documents online and which requests are red flags.
- Payday loan laws by state summarizes each state’s payday rules, with a link to every state regulator.
- Payday loan calculator estimates the fee, total repayment and APR for the amount you choose.
- What happens if you can’t repay a payday loan covers collections, payment plans and your rights.
- Payday loan alternatives compares cheaper options, including credit union loans and payment plans.
Updated October 2026. This page is general information, not financial or legal advice.